
RZOLV Technologies: The Commercialization Playbook

Nov 3, 2026 | RZL, Sophic Capital

License for Scale. Partner Selectively Where Upside Warrants.
Sophic Capital’s The Next Gold Rush Starts with Better Recovery Report outlined the industry problem and then From Stranded to Recoverable introduced RZOLV’s technology and potential benefits. That leaves the commercial question: if the platform works as intended, how does RZOLV turn it into a scalable business?
Management has simplified the commercial model into two principal paths – License and Partnership. The same chemistry, process IP and know-how can therefore be used either as a capital-light technology platform or, selectively, as a way to participate directly in project-level value.
The commercial takeaway is simple: RZOLV can pursue scale without funding a global manufacturing footprint. Licensing provides the capital-light path, while selective partnerships can capture more project-level value where the economics justify greater involvement.
Two Capital-Light Models Can Turn Technical Proof into Scale and Project-Level Upside
One of the more attractive parts of the thesis is what RZOLV does not intend to build. Creating a global mining-chemical company from scratch would require manufacturing plants, raw-material procurement, inventory, logistics, regulatory infrastructure, technical sales teams, product stewardship and significant working capital. RZOLV instead intends to use partners where that infrastructure already exists, while committing its own capital selectively.
License – Scale Through Existing Industry Infrastructure
RZOLV can license its chemistry, process IP, know-how and technical support to established reagent producers, mine operators, EPC/process companies, technology providers or mining contractors. Potential revenue includes upfront licence fees, royalties, reagent revenue and recurring technical income. This is the most capital-light and scalable path.
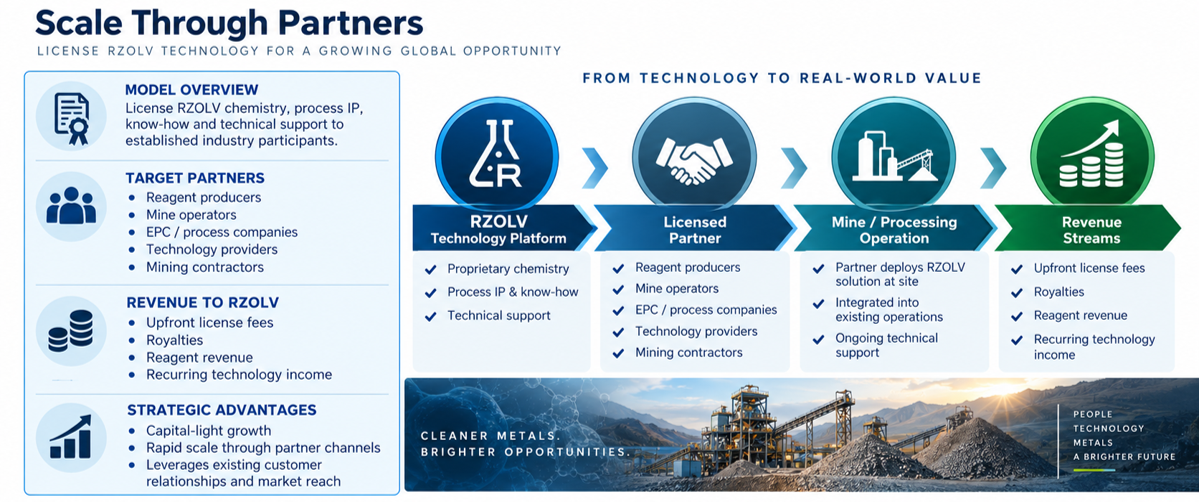
Management has identified established cyanide manufacturers and global mining-reagent companies as a primary route to market. The logic is additive rather than cannibalistic: an incumbent can continue selling cyanide where it remains the best answer while adding RZOLV for customer problems that fall outside cyanide’s effective window.
For an incumbent reagent supplier, the commercial incentive is not necessarily to replace profitable cyanide sales; it is to expand the product set into feeds, jurisdictions and customer problems that cyanide does not efficiently serve. Licensing, however, does not eliminate manufacturing diligence. A partner still needs confidence in raw-material availability, formulation and batch consistency, storage and handling, regional manufacturing, product stewardship and delivered reagent economics.
Internal RZOLV modelling has used annual licence fees plus an illustrative royalty of approximately 10% on partner-level reagent sales to demonstrate potential operating leverage. No partner has agreed to those terms, and actual economics could vary materially by territory, feedstock, customer and field of use. This revenue could include licensing, reagent economics, processing and project participation. The size of these projects could range anywhere from $10 to $100+ million, and with RZOLV taking a 10% royalty, that would make even the smallest projects material to the Company.
The October shareholder update illustrated how Partnership economics could work using a hypothetical 2-million-tonne tailings project at 1.0 g/t gold, 70% recovery, US$4,000/oz gold and a 5% royalty on gross recovered gold value; under those assumptions, potential RZOLV receipts would be about US$9 million ($12.6 million) over the processing life. Both examples are illustrative, not guidance or agreed commercial terms.
Partnership – Capture More Value Without Owning the Mine
RZOLV can work with asset owners, operators and technology partners on concentrates, tailings, spent heaps, complex ores and secondary materials through pilots, tolling, modular deployments, JVs or other project-specific structures. Potential economics can include processing fees, reagent sales, profit sharing, royalties, metal participation and project interests.
The key is staged capital exposure: screen the opportunity –> test the metallurgy –> pilot or field-validate the process –> define the commercial structure –> increase capital only where the data and project economics justify it. This allows RZOLV to participate in exceptional project-level value (particularly from above-ground material) without taking the full geological and development risk of building a conventional mine.
Solar-panel recycling is becoming a more tangible Partnership / License opportunity. RZOLV’s latest bench-scale work reported 99.9% silver extraction to solution from a prepared PV concentrate and 99.85% depletion of dissolved silver after five hours of electrowinning. The next work is to confirm the complete metal balance, saleable product quality, solution reuse, reagent consumption and operating costs, but the results show RZOLV can potentially address both dissolution and downstream metal recovery.
Management is also discussing a five-stage circular supply chain with prospective global partners: panel collection, dismantling and concentration, RZOLV dissolution, electrowinning, and refining/reuse. If formalized, that model could create recurring reagent, licensing and technical-support revenue without requiring RZOLV to own the collection or recycling infrastructure.

The hierarchy is straightforward: License for scale; Partner selectively for project-level upside.
Go-to-Market – Existing Industry Channels Can Compress the Path to Scale
RZOLV’s preferred go-to-market strategy is designed to leverage infrastructure that already exists. Global reagent manufacturers bring chemical production, logistics, mine-site sales and technical-service networks. EPC/process firms bring engineering and integration capability. Mine operators and toll processors bring feedstock and operating assets. Technology partners can complete downstream recovery or separation steps.
If RZOLV can supply the IP, chemistry and application know-how while established partners supply the global infrastructure, the Company can potentially scale faster and with less capital than if it attempted to own the entire value chain itself.
Partners Fill the Pieces RZOLV Does Not Need to Own
RZOLV has already begun assembling relationships around the portions of the flowsheet it does not intend to own internally.
EMEW Clean Technologies connects RZOLV’s upstream dissolution chemistry with project engineering, electrowinning and downstream metal-recovery expertise, supported by a network of nine global locations.
Alkemio Bioscience creates a potential pathway into selective rare-earth and critical-mineral separation.
Novamera explores integration with Surgical Mining, potentially connecting selective mining with smaller-scale modular processing.
Aurquest Alaska is now the clearest operating example of the Partnership model: Aurquest is funding equipment and hardware for the North Vancouver facility, has delivered approximately 2,150 kg of high-grade gold concentrates, and positive pilot results could support a larger toll-processing facility in Nome, Alaska. RZOLV retains the project IP.
Independent and government-supported organizations including SGS, UBC, NRC IRAP and MICA/CEMI, together with SR&ED support, add testing, technical and non-dilutive funding infrastructure around the platform.

These relationships now span a spectrum from technical collaboration to actual funding and feedstock commitment, giving RZOLV multiple ways to validate its capital-light model before material revenue.
2026 is the Bridge from Proving Chemistry to Commercial Adoption
That transition is now more concrete. Construction of the North Vancouver metal-recovery facility is scheduled to begin in November 2026, with commissioning expected by Q1 2027. Aurquest is funding equipment and hardware, NRC IRAP has approved up to $121,000 in non-dilutive support, and approximately 2,150 kg of high-grade gold concentrates has been delivered for the initial campaigns. The facility will integrate RZOLV leaching, EMEW electrowinning, and solution recycle with positive results potentially supporting a larger plant in Nome and a potential Alaska toll-processing joint venture. In parallel, management is progressing above-ground field opportunities, reagent-channel discussions and the solar-recycling partner network.
Management’s roadmap is to continue advancing concentrate-pilot capability, move toward above-ground field pilots involving spent heaps and selected tailings, remain highly engaged in discussions with major reagent and mining-industry participants, and broaden engineering, processing and downstream-recovery partnerships. The objective is commercial conversion: licensing agreements and selective project partnerships.

The Team Brings the Skills Needed to Move from Lab to Mine Site
Commercializing an industrial process requires more than chemistry. CEO Duane Nelson brings resource-company development and technology commercialization experience; CTO Hanif Jafari leads the hydrometallurgical and process-development work; and directors John McConnell, Mary Ellen Thorburn and Robert Archer add mine development, project finance, capital-markets and operating experience. That mix becomes more relevant as RZOLV moves from technical work toward partner negotiations, pilot deployment and commercial structures.
Above Ground Resources Fit a Capital-Efficiency Cycle
The strategic appeal of above-ground material is capital efficiency: much of the mining, crushing, movement and placement capital has already been spent. The investable question is what subset has sufficient grade, metallurgical response, solution access, ownership and permitting clarity, and economics to support retreatment. Even a small economic subset could matter, but value must be demonstrated project by project rather than inferred from uniform global grade and recovery assumptions.
If we take that one step further and apply an assumed grade of half a gram of gold per ton, and a 60% overall recovery assumption to visualize what the physical inventories could represent. At those assumptions, 10 billion tons of heat material corresponds to roughly 96 million ounces of recovered gold. The Tailings case is roughly 289 million ounces. Combined, approximately 386 million ounces. Again, these are mathematical scenarios, not resources, and not expected recoveries. But multiply that 386 million ounces by todays US$4,160 gold price, and you get roughly US$1.6 trillion.

Sophic Insights: Scale Through Partners, Keep the Upside Where It Matters
RZOLV’s commercial model is built for capital efficiency: License broadly for scale and Partner selectively where the technology can unlock enough recovered-metal value to justify greater project exposure.
That model fits a mining capex cycle likely to emphasize efficiency. Rather than build a global chemical company, RZOLV is building an IP platform that can plug into existing industry channels while retaining the option to share in project-level upside. The commercial question is whether counterparties move from evaluating the technology to committing capital, feedstock and contractual terms.
And that model is starting to show in practice. Aurquest is funding pilot equipment and providing feedstock, NRC IRAP is contributing non-dilutive capital, and the solar-recycling strategy is being built around partners that could handle collection, concentration, metal recovery and refining. Those structures let RZOLV focus capital on its chemistry, process IP and technical know-how.
The North Vancouver / Aurquest program is now the clearest near-term commercial wedge: construction is scheduled, feed is secured and the pathway could extend to a larger Nome toll-processing joint venture if pilot results are positive. Solar recycling provides a second emerging route to recurring licensing, reagent and technical-support revenue. Arizona, reagent-channel licensing and selected tailings or spent-heap projects provide additional shots on goal, while SEGR refractory and broader critical-mineral applications remain longer-term optionality.
Coming Up…
In the final report in this introductory series, we examine the evidence behind the story: the trials completed to date, the next pilot and scale-up programs, the commercial discussions already underway and the external validation events that could change how investors value RZOLV.
For More Research
Access more RZOLV Technologies research HERE
Sign up for Sophic Capital’s reports HERE
Disclosures
Sophic Capital client RZOLV Technologies Inc. [TSXV: RZL, OTCQB: RZOLF] has contracted Sophic Capital for capital markets advisory and investor relations services.
Disclaimers
The information and recommendations made available through our emails, newsletters, website and press releases (collectively referred to as the “Material”) by Sophic Capital Inc. (“Sophic” or “Company”) is for informational purposes only and shall not be used or construed as an offer to sell or be used as a solicitation of an offer to buy any services or securities. In accessing or consuming the Materials, you hereby acknowledge that any reliance upon any Materials shall be at your sole risk. In particular, none of the information provided in our monthly newsletter and emails or any other Material should be viewed as an invite, and/or induce or encourage any person to make any kind of investment decision. The recommendations and information provided in our Material are not tailored to the needs of particular persons and may not be appropriate for you depending on your financial position or investment goals or needs. You should apply your own judgment in making any use of the information provided in the Company’s Material, especially as the basis for any investment decisions. Securities or other investments referred to in the Materials may not be suitable for you and you should not make any kind of investment decision in relation to them without first obtaining independent investment advice from a qualified and registered investment advisor. You further agree that neither Sophic, its, directors, officers, shareholders, employees, affiliates consultants, and/or clients will be liable for any losses or liabilities that may be occasioned as a result of the information provided in any of the Material. By accessing Sophic’s website and signing up to receive the Company’s monthly newsletter or any other Material, you accept and agree to be bound by and comply with the terms and conditions set out herein. If you do not accept and agree to the terms, you should not use the Company’s website or accept the terms and conditions associated to the newsletter signup. Sophic is not registered as an adviser or dealer under the securities legislation of any jurisdiction of Canada or elsewhere and provides Material on behalf of its clients pursuant to an exemption from the registration requirements that is available in respect of generic advice. In no event will Sophic be responsible or liable to you or any other party for any damages of any kind arising out of or relating to the use of, misuse of and/or inability to use the Company’s website or Material. The information is directed only at persons resident in Canada. The Company’s Material or the information provided in the Material shall not in any form constitute as an offer or solicitation to anyone in the United States of America or any jurisdiction where such offer or solicitation is not authorized or to any person to whom it is unlawful to make such a solicitation. If you choose to access Sophic’s website and/or have signed up to receive the Company’s monthly newsletter or any other Material, you acknowledge that the information in the Material is intended for use by persons resident in Canada only. Sophic is not an investment advisor nor does it maintain any registrations as such, and Material provided by Sophic shall not be used to make investment decisions. Information provided in the Company’s Material is often opinionated and should be considered for information purposes only. No stock exchange or securities regulatory authority anywhere has approved or disapproved of the information contained herein. There is no express or implied solicitation to buy or sell securities. Sophic and/or its principals and employees may have positions in the stocks mentioned in the Company’s Material and may trade in the stocks mentioned in the Material. Do not consider buying or selling any stock without conducting your own due diligence and/or without obtaining independent investment advice from a qualified and registered investment advisor. The Company has not independently verified any of the data from third party sources referred to in the Material, including information provided by Sophic clients that are the subject of the report, or ascertained the underlying assumptions relied upon by such sources. The Company does not assume any responsibility for the accuracy or completeness of this information or for any failure by any such other persons to disclose events which may have occurred or may affect the significance or accuracy of any such information.
The Material may contain forward looking information. Forward-looking statements are frequently, but not always, identified by words such as “expects,” “anticipates,” “believes,” “intends,” “estimates,” “potential,” “possible,” “projects,” “plans,” and similar expressions, or statements that events, conditions or results “will,” “may,” “could,” or “should” occur or be achieved or their negatives or other comparable words and include, without limitation, statements regarding, projected revenue, income or earnings or other results of operations, strategy, plans, objectives, goals and targets, plans to increase market share or with respect to anticipated performance compared to competitors, product development and adoption by potential customers. These statements relate to future events and future performance. Forward-looking statements are based on opinions and assumptions as of the date made, and are subject to a variety of risks and other factors that could cause actual events/results to differ materially from these forward looking statements. There can be no assurance that such expectations will prove to be correct; these statements are no guarantee of future performance and involve known and unknown risks, uncertainties and other factors. Sophic provides no assurance as to future results, performance, or achievements and no representations are made that actual results achieved will be as indicated in the forward looking information. Nothing herein can be assumed or predicted, and you are strongly encouraged to learn more and seek independent advice before relying on any information presented.


Comments